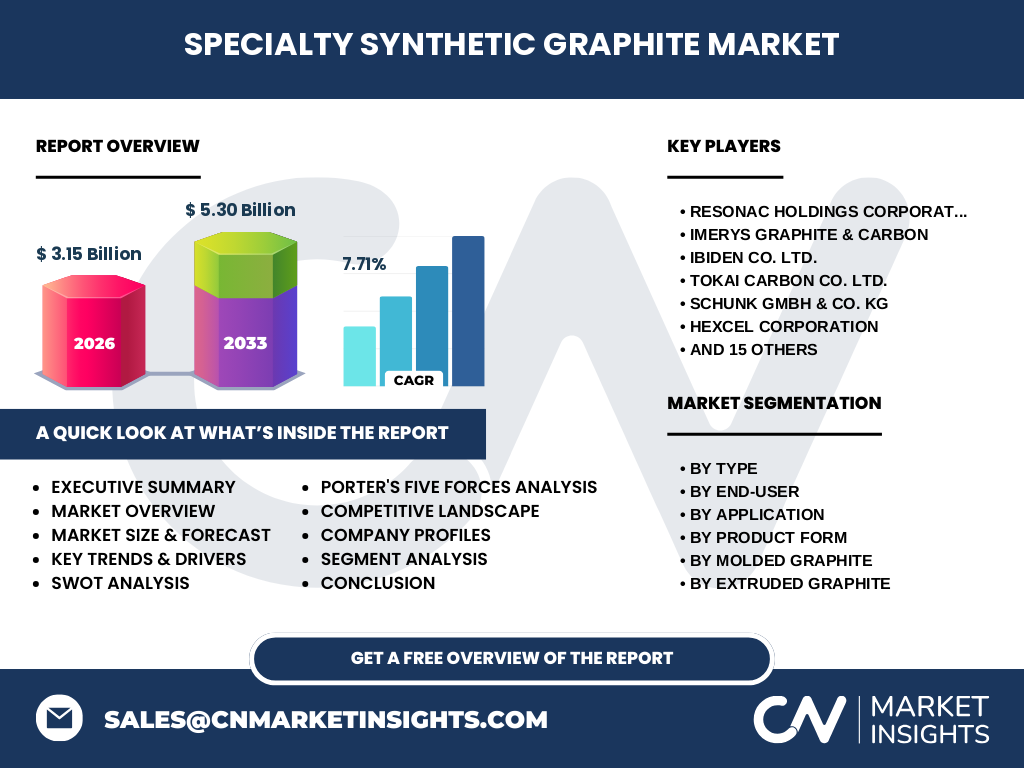
Market overview of the Specialty Synthetic Graphite Market
Our analysis indicates that the Specialty Synthetic Graphite Market represents a critical pillar in advanced materials engineering. Valued at 3.15 Billion in 2026, the sector encompasses high-purity carbon matrices engineered via graphitization of petroleum coke and pitch precursors. These materials are indispensable for extreme thermal management and electrical conductivity across cutting-edge industrial applications.
What are the key drivers, restraints, challenges, and opportunities in the Specialty Synthetic Graphite Market?
Structural demand from lithium-ion battery anodes and semiconductor manufacturing acts as a primary market catalyst. However, stringent environmental regulations governing graphitization emissions and volatile raw material costs pose notable restraints. Growth opportunities heavily favor suppliers optimizing energy-efficient graphitization furnaces and localized supply chains to bypass logistical bottlenecks.
Emerging trends and growth patterns in the Specialty Synthetic Graphite Market
The sector is witnessing a decisive shift toward ultra-high-purity grades required for silicon-anode battery blends. Key innovators like Vianode AS and Novonix Limited are pioneering sustainable synthetic graphite production. These sustainable methodologies significantly lower carbon footprints, aligning with stricter EU battery passport mandates.
How did the COVID-19 pandemic impact the Specialty Synthetic Graphite Market and drive its recovery?
Pandemic-induced supply chain fractures temporarily stalled industrial manufacturing and automotive assembly lines, depressing short-term demand. Recovery has been robustly propelled by aggressive governmental clean-energy stimulus packages in North America and Europe, accelerating investments in domestic electric vehicle supply chains and advanced energy storage infrastructure.
Competitive benchmarking and strategic dynamics in the Specialty Synthetic Graphite Market
Market concentration remains moderate to high, dominated by established chemical and carbon giants such as Resonac Holdings Corporation, Tokai Carbon Co. Ltd., and SGL Carbon SE. Competitive advantages hinge on proprietary purification technologies, long-term raw material supply agreements, and vertical integration spanning from petroleum coke processing to final machined components.
Executive summary of the Specialty Synthetic Graphite Market report
The Specialty Synthetic Graphite Market is on a steep upward trajectory, scaling from 3.15 Billion in 2026 to 5.30 Billion by 2033 at a CAGR of 7.71%. Growth is inextricably linked to technological advancements in semiconductors, photovoltaics, and energy storage, rewarding agile players with proprietary high-purity manufacturing capabilities.
Market forecast trajectory through 2033
Our research forecasts sustained expansion, driving the market from 3.15 Billion in 2026 to a projected 5.30 Billion by 2033. This consistent 7.71% CAGR reflects accelerating commercialization of wide-bandgap semiconductors, next-generation photovoltaic installations, and booming electric mobility adoption worldwide.
Segmentation analysis across types, end-users, applications, and product forms
Segmentation is categorized by type (Isotropic Graphite, Extruded Graphite, Molded Graphite), end-user (Electronics, Energy, Automotive, Industrial, Aerospace), application (Photovoltaic, Semiconductor, EDM, Foundry), and product form (Powders, Fibers, Composites, Specialty Grades). Each segment addresses precise thermal, electrical, and mechanical tolerances demanded by modern engineering.
Geographic distribution and regional performance dynamics
Asia-Pacific dominates consumption, driven by extensive semiconductor fabrication facilities in Taiwan, South Korea, and China. Meanwhile, North America and Europe exhibit specialized demand focused on aerospace defense applications, advanced automotive lithium-ion manufacturing, and high-purity photovoltaic crystal-pulling equipment.
In-depth regional review of the Specialty Synthetic Graphite Market
Regional performance highlights Asia-Pacific as the undisputed volume leader due to concentrated battery cell gigafactories and electronics manufacturing hubs. Concurrently, North American and European markets prioritize technological supremacy, investing heavily in high-purity isotropic grades for EU-mandated clean energy transitions and domestic supply resilience.
Company profiles and strategic positioning of leading industry participants
Industry leaders occupy distinct strategic niches. Toyo Tanso Co. Ltd. and Poco Graphite Inc. excel in ultra-fine isotropic grades for semiconductor tooling. Meanwhile, players like GrafTech International Ltd. and Mersen S.A. focus on heavy industrial, metallurgical, and high-temperature furnace applications requiring robust thermal stability.
Porter's Five Forces analysis of the Specialty Synthetic Graphite Market
The threat of new entrants is mitigated by high capital expenditure requirements for extreme-temperature graphitization furnaces. Bargaining power of suppliers is moderate, constrained by petroleum coke availability, while buyer power is tempered by the specialized, custom-machined nature of high-performance specialty grades.
SWOT analysis of the Specialty Synthetic Graphite Market ecosystem
Strengths include exceptional thermal and chemical resistance properties. Weaknesses involve energy-intensive production cycles. Opportunities emerge from silicon-anode battery developments and green energy subsidies. Threats center on geopolitical trade friction impacting raw material access and fluctuating synthetic precursor costs.
Value chain analysis from raw materials to end-users
The value chain initiates with petroleum coke and pitch procurement, advancing through thermal baking, impregnation, and multi-week graphitization cycles at temperatures exceeding 2800°C. Finished blocks undergo precision machining by specialists like Schunk GmbH & Co. KG before reaching semiconductor and energy end-users.
Investment insights and high-potential areas for capital allocation
High-potential capital allocation targets greenfield graphitization facilities utilizing renewable energy sources and proprietary purification processes. Investors should focus on companies scaling production of fine-grain isotropic graphite tailored for extreme ultraviolet lithography and next-gen electric vehicle battery chemistries.
Conclusion and key takeaways for industry stakeholders
Reaching 5.30 Billion by 2033 at a 7.71% CAGR underscores the indispensable nature of specialty synthetic carbon materials. Long-term success relies on mastering sustainable graphitization, securing stable precursor streams, and forging deep technological partnerships with semiconductor and energy storage leaders.
Research methodology and triangulation of market baseline estimates
Our baseline estimates are rigorously triangulated by combining global trade registry data, primary stakeholder interviews with C-suite executives from firms like Imerys Graphite & Carbon and Superior Graphite Company, and secondary macroeconomic indicators tracking semiconductor fab expansions and EV adoption metrics.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue estimations from 2026 to 2033 across specified isotropic, extruded, and molded segments. Limitations include unforeseen geopolitical trade restrictions and sudden shifts in environmental compliance costs associated with high-temperature industrial graphitization operations worldwide.
Recent developments, strategic partnerships, and product launches
Recent market activity highlights aggressive capacity expansions by companies like Ibiden Co. Ltd. and strategic joint ventures aimed at producing battery-grade synthetic powders with lower carbon intensity. These moves reflect intense industry adaptation to stringent environmental policies and soaring electrification demands.